How St. Louis Investors Negotiate When Inventory Surges
Sep 18, 2026
Written by David Dodge
More Listings, Fewer Easy Deals: How to Negotiate in St. Louis
"I'm finding properties, but the numbers still don't work." If that's been running through your head on every drive-by this month, you're reading the right thing.
That sentence has been showing up in a lot of investor group chats around St. Louis lately, and it's not because people have forgotten how to run numbers. It's because the market underneath those numbers has quietly changed shape. There's more to choose from than there's been in years, sellers are cutting prices at a rate we haven't seen since before the pandemic run-up, and yet somehow the spreadsheet still says "pass" more often than it says "go."
That contradiction is the whole story right now. More inventory is supposed to mean easier deals. In St. Louis, in September 2026, it hasn't worked out that way — and understanding exactly why is the difference between an investor who's frustrated and one who's quietly restocking a pipeline while everyone else complains that "there's nothing out there."
The Numbers Behind the Headache
Start with what's actually happened to supply. Across the Greater St. Louis metro, total homes listed for sale reached 9,864 units heading into September 2026, a 13.9% jump from the same point in 2025. Zoom into the City and County specifically and the picture is even sharper: active single-family inventory climbed 15.2% year-over-year to 3,563 homes by late August, and roughly 17.9% of those active listings across the metro had already taken at least one price cut.
On paper, that's an investor's dream. More product, more sellers blinking first. Except the second half of the data tells a stubborn, almost contrarian story. The combined City and County single-family median sold price still climbed 5.9% year-over-year to $350,000, and in St. Louis County specifically, closed transactions hit a median sold price of $320,000, up 8.47% from $295,000 the year before. Meanwhile, the median list price for active inventory actually fell 13.76% to $250,000, down from $289,900 a year earlier.
Read those two numbers side by side and you can see exactly what's happening. Sellers are listing lower on average — plenty of tired, dated, or overpriced product is finally coming to market — but the homes that actually cross the finish line and close keep selling for more. It's not one market moving in one direction. It's two markets moving in opposite directions at the same time, and most of the frustration investors feel right now comes from treating it like one.
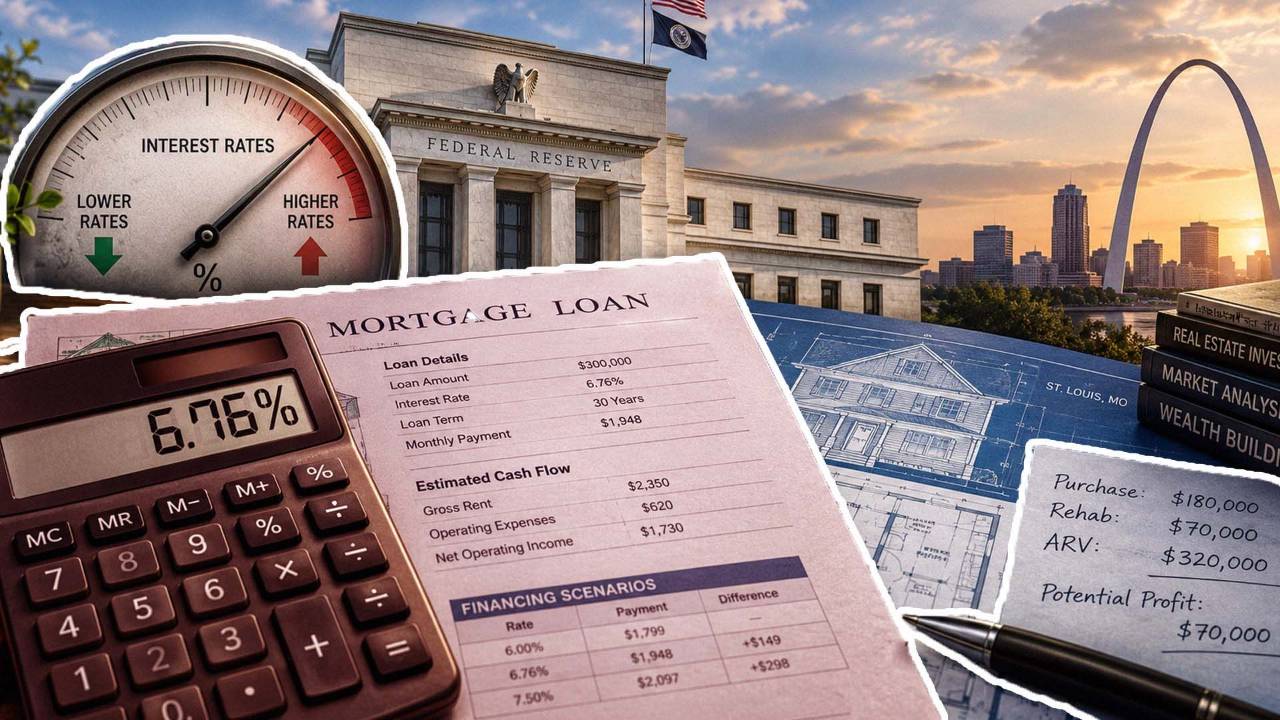
Layer financing on top of that and the squeeze gets real. Freddie Mac had the 30-year fixed rate at 6.76% as of September 10, 2026, up slightly from the week before and roughly 40 basis points higher than the same week a year ago. That single number touches every part of your deal — what a retail buyer can qualify for on your flip, what a tenant's rent needs to cover on your rental, and what your own hard money or DSCR loan is going to cost you while you own the thing.
Median single-family closed price by submarket, late summer 2026. Even with inventory up double digits across the region, closed prices kept climbing everywhere — just at very different speeds.
Source: HouseSoldEasy.com, "Investors Win in Two Tracks as STL Inventory Rises in 2026" & "St. Louis Market 2026: 3 Must-Make Investor Adjustments," September 2026.
Why Profitable Deals Are Getting Harder to Find
None of this is random. There's a logic to why more inventory hasn't translated into more workable deals, and once you see the pattern you'll start noticing it on nearly every listing you pull up.
Seller expectations are moving slower than the market.
A lot of the people listing homes this fall bought or refinanced during the ultra-low-rate years, and their sense of what their house is "worth" is still anchored to 2021 and 2022 bidding wars. They price for that market and then act surprised when today's buyers — who are financing at 6.76% instead of 3% — won't chase them there.
Asking prices are still aspirational, even after cuts.
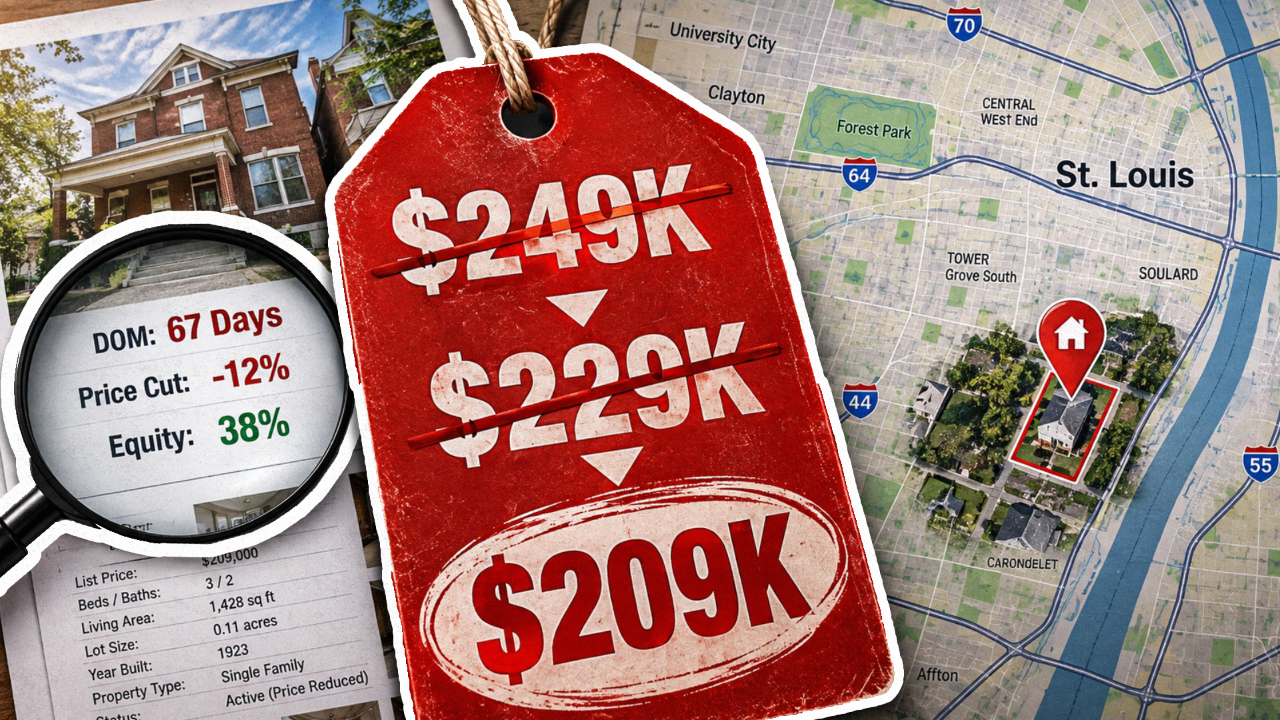
With nearly 18% of metro listings showing at least one price reduction, it's tempting to assume sellers have gotten realistic. Most haven't — not on the first cut. Sellers frequently start 5-10% above the comps to "test the market," and by the time they finally adjust, they've burned through 30, 40, sometimes 45 days of carrying costs they'll never get back.
Rehab budgets are quietly out of date.
If your cost-per-square-foot assumptions for a kitchen, bath, or roof haven't been updated since before 2023, you're underwriting on old math. Labor and material costs have climbed steadily, and a project that looked like a cosmetic refresh from the street too often turns into a structural surprise once the drywall comes down — especially in the older housing stock that dominates neighborhoods like Tower Grove South, the Central West End, and Soulard.
Financing costs are eating margin from both ends.
Hard money running 11-13%, DSCR loans in the 7.5-8.5% range, and conventional exit financing near 6.76% mean every extra month you hold a property and every extra point on your rate is coming straight out of your profit line, not just your patience.
Holding costs add up faster than people expect.
Property taxes, insurance — which has climbed sharply across Missouri in the past couple of years — utilities, and any HOA dues quietly compound the longer a rehab drags or a rental sits between tenants.
ARV assumptions are stuck in an old cycle.
Pulling comps from 2021 or 2022 without adjusting for what today's buyers can actually afford at 6.76% financing is one of the fastest ways to overpay for a deal that looked fine on a spreadsheet.
Put all of that together and you get thin margins with almost no room for error. A deal that pencils out at 6.76% financing can flip from profitable to break-even with a single $5,000 repair overrun or a 30-day delay to close.
The Five-Part Deal Diagnosis
Before you write an offer on anything in St. Louis right now, it's worth running every property through the same five-part checkup. Skipping any one of these five is usually where a "good deal" quietly turns bad.
1. Property — what is it actually worth?
Pull at least three to five closed comps from the last 90 days, within half a mile and a similar square footage and bed-bath count. Adjust for real condition differences — an updated kitchen, a newer roof, a finished basement — and land on two separate numbers: what the home would sell for today, as-is, and what it would sell for after repairs (your ARV). Stay conservative. If your comps cluster between $210,000 and $235,000, underwrite at $215,000, not $230,000.
2. Repairs — what does it really need?
Walk the property yourself, or send a contractor before you write an offer, not after. Split the scope into cosmetic items — paint, flooring, landscaping — and structural items — roof, foundation, sewer lateral, electrical, HVAC. Get written estimates on the big-ticket items, and build in a 15-20% contingency for whatever's hiding behind the walls, because in a metro with as much prewar housing stock as St. Louis, something usually is.
3. Seller — what problem are they actually trying to solve?
Price is rarely the whole story. Figure out whether the seller is driven by price, timing, certainty, or plain convenience. Are they racing a deadline — a job relocation, an estate settlement, a foreclosure timeline, or two mortgage payments they can't keep carrying? Do they have the cash to handle municipal occupancy inspection repairs themselves? Would they honestly rather take a fast, certain, as-is cash offer than chase a higher number from a retail buyer with financing and inspection contingencies attached?
4. Financing — what does your capital actually cost?
Get specific on both ends. What's your acquisition cost — hard money, private money, a DSCR loan, or cash? What's your exit — a conventional refinance near 6.76%, a DSCR refi in the 7.5-8.5% range, or a straight cash sale to a retail buyer? Then run the actual monthly debt service at real rates. Not a rounded estimate, not last year's rate. The real number, today.
5. Exit — who's actually going to buy or rent it?
If you're flipping, who's your retail buyer at this price point, and what mortgage rate will they be facing when they go to qualify? If you're holding as a rental, what does market rent actually support in this specific submarket, and does that rent clear debt service at a 7.5-8.5% DSCR rate? If you're wholesaling, do you genuinely have cash buyers lined up who'll still pay your assignment fee once they've priced in today's financing costs?
Do the Math Backward, Not Forward
The single biggest shift investors need to make in this market is where they start the calculation. Most people still start with the list price and work forward, asking "can I make this work?" That's backwards. Start with your exit and work backward to a maximum number you can pay.
The example below is illustrative math to show how the formula works — not a specific active listing or actual St. Louis market statistic.
Say a property has an ARV of $240,000 and needs $35,000 in repairs. You're financing acquisition with hard money at 12% for nine months on a $180,000 loan, which runs about $16,200. Six months of taxes, insurance, and utilities adds roughly $5,400. Selling costs — 6% plus closing — come to about $16,800 on that $240,000 exit price. You want a $25,000 profit, and you build in a $3,500 contingency, or 10% of your repair budget.
Run the formula: $240,000 minus $35,000 minus $16,200 minus $5,400 minus $16,800 minus $25,000 minus $3,500 leaves a maximum acquisition range of $138,100. If the seller wants $165,000, the deal simply doesn't work at those assumptions. At that point you have four honest options: negotiate the price down toward $138,000-$145,000, find a way to lower the repair number (unlikely if your estimate was accurate), accept a smaller profit and the added risk that comes with it, or walk.
Negotiate on More Than Price
Price is only one lever in a negotiation, and in a market where sellers are anchored to numbers they can't get, it's often the least flexible one. The levers below tend to move faster — and they cost you far less than chasing a seller down on price alone.
|
Lever |
How to Use It |
What It Sounds Like |
|---|---|---|
|
Closing Timeline |
Offer speed or flexibility, matched to what the seller actually needs. |
“We can close in 14 days, or wait 45 if you need time to move.” |
|
Repairs |
Buy fully as-is, including municipal occupancy inspection items. |
“We’ll buy as-is and handle every occupancy repair ourselves.” |
|
Possession |
Offer a post-closing rent-back or early occupancy window. |
“You can stay 30 days after closing at no cost to you.” |
|
Certainty |
Minimize or waive financing and appraisal contingencies. |
“Cash offer, no appraisal, no financing contingency.” |
|
Inspection Scope |
Limit objections to major structural or safety issues only. |
“We’ll only object over $5,000 in foundation, roof, or sewer repairs.” |
|
Proof of Funds |
Show cash in escrow to remove lender delay as a risk. |
“Funds are already in escrow—no lender timeline to worry about.” |
|
Seller Terms |
Structure creative terms when they genuinely help the seller. |
“A 12-month seller carry at 7% could help with your tax planning.” |
A quick but important note here: none of this works, or should work, as manipulation. Every one of these levers is a real trade — you're offering something the seller values (speed, certainty, convenience) in exchange for something you need (price, terms, flexibility). And on anything involving seller financing, leasebacks, or other creative structures, loop in a qualified real estate attorney, lender, or tax advisor before you put it in writing.
What This Shift Means, Beginner or Experienced
If you're newer to investing in St. Louis, your first ten to twenty deals will teach you more than any course or podcast episode — but only if you let the market teach you the right lessons. Underwrite conservatively: assume higher repair costs, longer holding periods, and more cautious ARVs than feel comfortable. Walk away from anything that looks marginal on paper, because marginal deals get worse once real life touches them, not better. And spend real time building relationships with contractors, lenders, and title companies who actually understand how investors work — that network will save you more money than any negotiating tactic.
If you've already closed a number of deals, you already know how to run the numbers. Your edge right now is elsewhere. It's in systematically following up on offers that got rejected 60 to 90 days ago, since seller circumstances change fast in a market like this. It's in negotiating creatively across timing, certainty, and terms instead of only pushing on price. And it's in targeting your outreach toward the sellers most likely to be feeling the squeeze — long days on market, multiple price cuts, signs of vacancy, or an estate sale in progress.
A St. Louis Case Study
Illustrative example — not an actual listing
Picture a three-bedroom, two-bath brick ranch in Affton, a solid working-class pocket of south St. Louis County. It's listed at $289,900, has been sitting for 41 days, and already took one price cut down from $309,900. Walking it, you find it needs roughly $40,000 in work: kitchen, both baths, flooring, paint, and a roof that's past its useful life.
Your comps put the ARV at $345,000. Run the formula: $345,000 in ARV, minus $40,000 in repairs, minus about $20,700 in hard money financing (12% for nine months on a $230,000 loan), minus roughly $6,300 in six months of holding costs, minus about $24,150 in selling costs at 6% plus closing on that $345,000 exit, minus a $30,000 desired profit, minus a $4,000 contingency at 10% of repairs. That lands your maximum acquisition range at $219,850.
The current list price is $289,900 — a $70,050 gap. That's not a reason to walk, at least not yet. Acknowledge the price reduction and the extended days on market when you talk to the agent or seller. Present your numbers openly rather than lowballing blind: "Based on current financing costs and today's repair pricing, here's what this deal actually supports." Then offer $225,000, as-is, cash, with a 14-day close, no inspection objections beyond major structural items, and a 30-day free rent-back if the seller needs it. If they say no, ask what price or terms would work for them — and put the property on a 60-day follow-up list rather than crossing it off entirely.
Build a Follow-Up System, Not Just an Offer Pipeline
Most investors treat a rejected offer as a dead end. In a market moving like St. Louis's is right now, it's closer to a seed you plant and come back to. The pipeline looks like this:
- Lead — a property surfaces through MLS, direct mail, driving for dollars, or a referral.
- Conversation — you call the listing agent or the seller directly and start asking real questions.
- Motivation — you figure out what the seller is actually optimizing for: price, timing, certainty, or convenience.
- Offer — you submit a written offer built off your Maximum Acquisition Range, not off the list price.
- Follow-up — if it's rejected, you ask what would have worked, and you set a 30-day reminder.
- Renegotiation — when circumstances shift — another price cut, a failed contract, more days on market — you re-approach with an updated offer.
- Contract — once it's accepted, you move fast. Delays are where deals quietly die.
The reason this matters so much in today's St. Louis market is that rejected offers from two or three months ago aren't static. That seller has now paid another two or three months of mortgage, taxes, insurance, and utilities on a house that didn't sell. There may have been another price cut, or a buyer's financing fell through and the seller is starting over. Life circumstances shift — a job change, a relocation, a health issue, an estate finally moving toward settlement. And other investors who made offers around the same time as you may have walked away over financing or inspection issues you don't even know about.
If you've got a stack of offers from June, July, and August 2026 that went nowhere, that stack is worth another look before you spend more time hunting for brand-new leads.
The Bottom Line
More listings and widespread price reductions in St. Louis don’t automatically hand investors easier deals—and the market data makes that contradiction plain. Inventory across St. Louis City and County has jumped more than 15%, nearly 18% of all metro listings have taken at least one price cut, and yet median closed prices continue their climb: $350,000 combined across City and County, and $320,000 in the County alone. Meanwhile, borrowing costs hovering near 6.76% for conventional financing, 7.5%–8.5% on DSCR loans, and 11%–13% in hard money leave virtually zero room for error. When capital is expensive and retail buyers are constrained, margin compression happens fast.
This isn't a single market slowing down; it's a split market where dated, overpriced inventory piles up on one side, while high-quality, fully finished assets command top dollar on the other. Relying on 2021-era comps, estimating rehab costs with outdated benchmarks, or starting an underwriting model from the list price will almost guarantee a pass on paper—or worse, a costly mistake on site.
The investors consistently winning deals in this climate aren't sitting on the sidelines hoping the math magically resolves itself. Instead, they are winning through operational discipline across five key areas:
-
Underwriting Backward from the Exit: Every acquisition begins with the hard exit reality—factoring real debt service, a minimum 15%–20% repair contingency, holding carrying costs, and transaction fees—to dictate a strict Maximum Acquisition Range before price discussions even start.
-
Decoupling Price from Negotiation: Recognizing that sellers anchored to 2021 numbers will resist heavy price discounts, savvy buyers pull non-monetary levers: absorbing municipal occupancy inspections, closing fast with escrow-backed cash, waiving minor inspection objections, or offering free post-closing rent-backs.
-
Diagnosing the Seller's Core Pain Point: Pinpointing whether a seller is solving for speed, estate settlement, two carrying mortgages, or pure certainty allows buyers to craft offers that solve the real logistical bottleneck rather than haggling over asking price alone.
-
Building an Active Pipeline on Rejections: Treating "no" as a 30-to-60-day delayed opportunity. As rejected properties rack up cumulative holding costs, endure financing fall-throughs, and face second-round price cuts, systematic follow-ups convert stale listings into viable purchases.
-
Maintaining Rigid Acquisition Discipline: Walking away the moment numbers exceed strict return thresholds, knowing that marginal deals in older brick and prewar housing stock deteriorate quickly under real-world conditions.
The St. Louis market isn't starved of opportunity—it's filtering out lazy underwriting. Sustainable deal flow right now isn't created by waiting for the market to hand out discounts; it’s manufactured by operators who know precisely what a property can support, protect their margins upfront, and structure solutions that meet sellers where they are.
Ready to Buy or Sell in St. Louis? House Sold Easy Has You Covered!
Whether you're thinking about listing your home or exploring a cash offer, it's worth understanding all of your options before making a decision. The right choice depends on your timeline, your property's condition, and your goals. Contact House Sold Easy to discuss your situation and see what makes the most sense for you.Our St. Louis experts know every corner of this city and will make buying your dream home or selling your high-end property a breeze. Don’t miss out on the hottest market in the U.S.! Contact House Sold Easy today and let’s make your real estate goals happen!