Fed Decision Week: St. Louis Real Estate Investor Guide 2026
Sep 17, 2026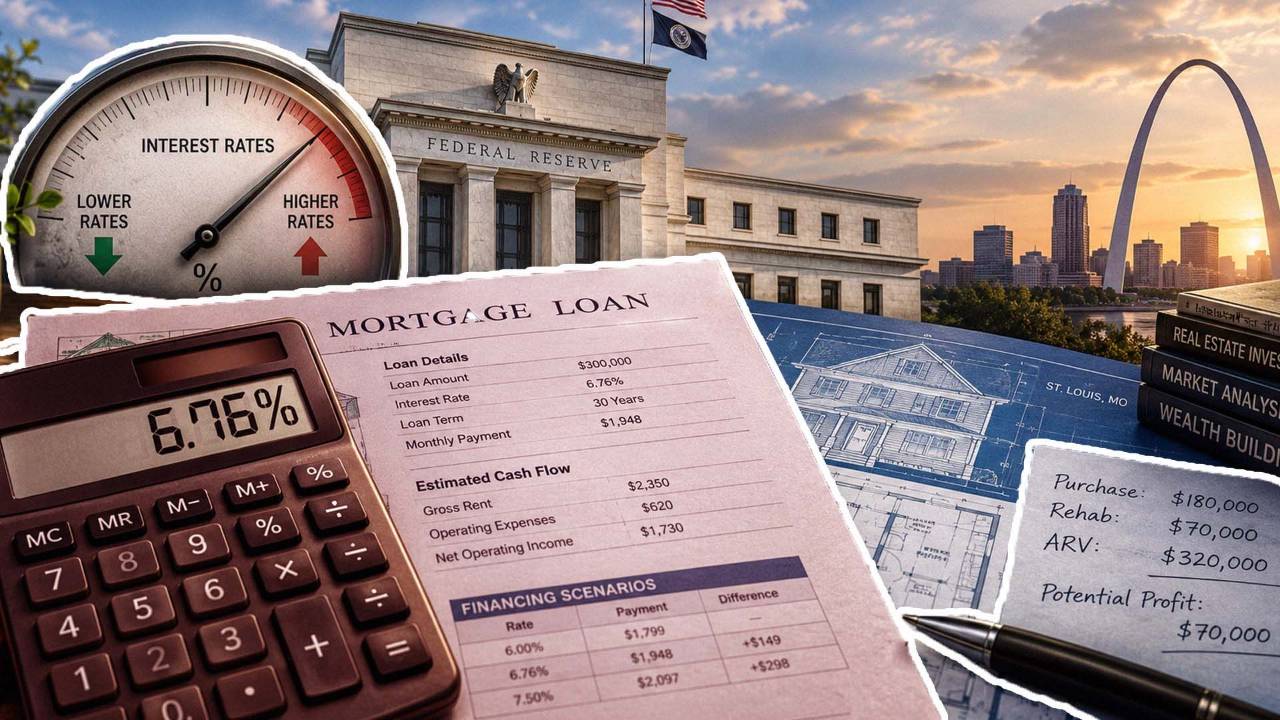
Written by David Dodge
Fed Decision Week: What St. Louis Real Estate Investors Should Watch
The Fed hands down its rate call this afternoon, but the number St. Louis investors actually need to underwrite by is already sitting in Freddie Mac's mailbox. Here's how to read the week without getting distracted by it.
If you buy, flip, or hold rental property anywhere from South City to St. Charles County, today is one of those days where your group chat is probably lighting up. The Federal Reserve wraps its two-day policy meeting this afternoon, and for the first time in over a year, nobody — not the big banks, not the bond desks, not the people whose entire job is guessing this stuff — is totally sure what happens next.
Here's the thing, though: whatever gets announced at 2:00 p.m. Eastern today won't change the math on the deal you're underwriting this week. The financing environment St. Louis investors are actually operating in has already been set by the bond market, and it's tighter than a lot of pro formas assume. This piece walks through where rates stand right now, what today's meeting could still move, and — more importantly — how to stress-test your St. Louis deals so they survive regardless of what Chair Warsh says at his podium.
Where Things Stand Heading Into the Decision
The Federal Open Market Committee's two-day meeting runs September 15–16, with the rate decision and updated Summary of Economic Projections released at 2:00 p.m. ET on the 16th, followed by Chair Kevin Warsh's press conference at 2:30 p.m. Going into the meeting, the federal funds target sits at 3.50%–3.75%, a level the committee has held since it was reaffirmed at the July meeting on a divided 9–3 vote, with three regional bank presidents pushing for a hike rather than a cut.
What's changed since July is the tone of the betting. Trading desks have moved a lot of chips onto the "hike" side of the table in the past two weeks. One market desk pegged the odds of a quarter-point hike to 4.00% at roughly 86% to 90% following the September 11 inflation print, up from about 70% just a day earlier. That's a meaningful shift from where the conversation was even a few weeks back, when a hold looked like the obvious base case, and the July dissents were treated as a minority view. Not everyone agrees on where this lands, and that disagreement is the story. J.P. Morgan Wealth Management expects a 25-basis-point hike, while Goldman Sachs has called a September hike "very unlikely" and expects the Fed to hold through the rest of the year — a genuine split among major forecasters, not just noise. Chair Warsh's first Jackson Hole keynote came on August 28, just under three weeks before today's decision, and he has consistently declined to offer forward guidance since taking office — which is exactly why this meeting has more genuine suspense than most.
Why this matters for the deal in front of you: A rate decision is a headline. Your acquisition and exit financing costs are a number on a spreadsheet, and that number is already set by the mortgage market — not by what gets announced this afternoon. St. Louis investors who wait for "clarity" from the Fed before running their numbers are underwriting off the wrong input.
It's worth sitting with how unusual this meeting actually is. For most of the past two years, Fed meetings have been fairly easy to forecast — a hold here, a well-telegraphed cut there. This one is different. Prediction markets tracking the September outcome have shown real money split across hold, hike, and even a token amount on a cut, with pricing shifting noticeably in the two weeks leading up to today. That kind of split doesn't happen when the outcome is obvious. It happens when the data itself is sending mixed signals — inflation running hotter than target, while other parts of the economy still look steady enough that the committee doesn't have an easy consensus to fall back on. For a St. Louis investor, the lesson isn't to try to out-guess the committee. It's to build a plan that doesn't depend on guessing right.
The St. Louis Market You're Actually Investing In
Zoom out from the Fed for a second and look at what's happening on the ground here in the metro. September 2026 has turned into what a lot of local brokers are calling a two-track market. Across the region, total homes listed for sale reached 9,864 units, an increase of 13.9% compared to the same period in 2025 — and yet prices haven't cracked the way rising inventory usually suggests they should. In fact, the combined City and County single-family median sold price rose 5.9% year-over-year to $350,000, while the broader metro median sale price climbed 3.7% to $310,000.
What's driving the split is condition and location, not scarcity. Move-in-ready homes in the right school districts are still going fast — some under contract in under a week — while dated or deferred-maintenance properties are sitting for a month and a half or longer before sellers cave on price. On the investor side specifically, active inventory across the metro expanded 15.2% to 5,850 units this September, shifting leverage away from aggressive sellers for the first time in years. Rehabbers working the City, St. Louis County, St. Charles County, and Jefferson County are all seeing the same pattern: turnkey product in Tower Grove South, Shaw, Soulard, and the Central West End is still competitive, while older stock with real capital needs is where the negotiating room has opened up.
That expanding inventory is a direct response to financing costs, not a coincidence. It's the same story national data is telling — homebuyer purchasing power erodes every time rates climb another quarter point, and sellers who don't need to move are choosing to sit rather than chase a shrinking buyer pool.
Drill down another level and the neighborhood-by-neighborhood picture gets even more useful for underwriting. In St. Charles County, most of the housing stock was built from the 1980s through today, which means fewer of the deferred-maintenance headaches that show up in older City inventory — and it shows in the numbers, with sub-$350,000 homes in the Fort Zumwalt and Francis Howell school districts still regularly drawing multiple offers even as rates climb. Compare that to pockets of the City itself, where older brick flats and homes needing real capital work are sitting on the market noticeably longer, often requiring a price cut or seller concession before they move. For rehabbers, that gap between "turnkey and desirable" and "needs work and can wait" is exactly where the opportunity — and the risk — is concentrated right now. Buy the right property in the wrong condition category, and you're fighting the market instead of riding it.
It's also worth noting that St. Louis isn't behaving like a market in freefall, even with rates where they are. Redfin's tracking shows St. Louis homes receiving an average of two offers and selling in around 16 days over the trailing three months, with the median sale price up 7.1% year-over-year — hardly the picture of a market buyers have abandoned. That resilience is a double-edged sword for investors: it means well-priced, well-conditioned properties still move fast, but it also means there's less room for lazy underwriting. You can't count on a soft market to bail out an overpriced acquisition.
Mortgage Rates Already Priced In the Uncertainty
This is the part that gets lost in Fed-decision coverage: mortgage rates move on Treasury yield expectations, and those expectations have already been drifting higher for weeks — well ahead of today's announcement. Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed-rate mortgage at 6.76% for the week ending September 10, 2026, up from 6.71% the week prior and 6.35% a year earlier. The 15-year fixed averaged 6.09%, also up from the previous week. That 30-year figure is the highest weekly PMMS reading since mid-2025.
And the trend hasn't reversed since that release. Daily lender rate-sheet tracking from Mortgage News Daily showed the 30-year fixed climbing further to 7.17% by September 14, ahead of the Fed's own decision — a reminder that the bond market often front-runs the FOMC rather than waiting for it to act. If you want to track this yourself going forward, the Federal Reserve Bank of St. Louis publishes the weekly 30-year fixed mortgage series through its FRED database, updated every Thursday alongside the Freddie Mac release — a genuinely useful bookmark for anyone underwriting deals in this market.
30-Year Fixed Mortgage Rate — Weekly Average
Freddie Mac Primary Mortgage Market Survey, July 23 – September 10, 2026
Source: Freddie Mac PMMS weekly averages, compiled via Mortgage News Daily and the St. Louis Fed's FRED database. Eight straight weeks of upward drift, well before today's FOMC announcement.
The Fed Doesn't Set Your Mortgage Rate — Here's What Actually Does
This trips up a lot of newer investors, so it's worth spelling out plainly: the Federal Reserve doesn't set mortgage rates directly. It sets the overnight rate banks charge each other, and that ripples outward through a chain that looks roughly like this:
Fed policy expectations → Treasury yields → mortgage-backed security pricing → mortgage rates → buyer affordability → your financing costs → your deal margin.
Bond traders don't wait for the Fed to act before repricing — they trade on what they expect the Fed to do, sometimes weeks in advance. That's exactly what's happened here: the 30-year fixed climbed in eight of the last eight weeks, mostly on shifting rate-hike odds rather than any actual Fed move. By the time the FOMC statement drops this afternoon, most of the expected outcome is probably already baked into the number your lender will quote you tomorrow.
For investors, that transmission chain keeps going past the retail mortgage. Hard money and DSCR loans used for acquisitions and bridge financing typically price 150 to 300 basis points above the conforming 30-year rate, depending on your lender relationship and the deal's leverage. So when the PMMS heads toward 6.8% or higher, St. Louis investors should expect acquisition paper in the high-single-digits and exit DSCR financing not far behind it.
There's a second, quieter effect worth flagging too: elevated rates don't just raise your own borrowing cost, they raise your competitor's cost as well, and that changes bidding behavior across the board. When acquisition financing gets more expensive for everyone chasing the same North City or St. Charles County property, the pool of investors willing to stretch on price shrinks. That can actually work in your favor if you're financially prepared to move — fewer competing offers, less pressure to waive contingencies, and more negotiating room on repair credits. The investors who get hurt in this environment aren't the ones facing higher rates; they're the ones who didn't adjust their offer price to reflect them.
What This Means, Investor Type by Investor Type
Flippers
Your exit depends on a retail buyer who can actually qualify at today's rates — not the rates from your last comp set. Purchasing power at 6.76%–7.17% is meaningfully lower than it was even a year ago, which squeezes the buyer pool hardest above roughly $350,000 in most St. Louis submarkets. Two adjustments matter right now: pull your ARV comps from closings in the last 60–90 days only, and treat your holding period as a cost center — every extra month of hard-money carry at 11%–13% eats into a margin that's already thinner than it was in 2023–2024.
There's also a staging and marketing angle worth taking seriously in this rate environment. With fewer qualified buyers shopping above the $350K mark, competing on price alone gets harder. Flippers who invest in genuinely move-in-ready finishes — the kind that let a buyer skip a renovation loan altogether — tend to hold their days-on-market numbers even as the broader pool tightens. A half-finished flip in this market is a much harder sell than it was two years ago, when buyers had more room in their budgets to absorb unfinished work themselves.
Rental (Buy-and-Hold) Investors
Debt service is your whole game, and DSCR pricing is tracking the PMMS higher. A $150,000 DSCR loan at 8% runs roughly $1,100 a month in principal and interest before you've paid a dime of taxes, insurance, or maintenance. Run your numbers at the rate your lender is quoting this week, not the rate you got on your last deal. If a property's rent doesn't clear debt service plus a realistic reserve at today's DSCR pricing, it's not a deal — it's a bet on a rate cut that may not come.
Rental investors also have an advantage the flip-and-sell crowd doesn't: you're not racing a retail buyer's qualification window. That gives you more room to be patient on acquisition price, since a slightly softer purchase number does more for your long-term cash flow than chasing a marginal deal just to keep capital deployed. In neighborhoods like Tower Grove South, Shaw, and Soulard, where renter demand has stayed consistent even as sale prices climbed, buy-and-hold math tends to hold up better than flip math does at today's rates — worth keeping in mind if you're deciding which strategy to lean into for the next few quarters.
BRRRR Investors
This is where the most optimistic underwriting tends to hide. Don't assume your refinance will land at 5.5% or 6% just because that's where rates sat a couple of years ago. Underwrite the refi leg at 7.5%–8.5% DSCR pricing, and stress-test whether the deal still cash flows if your ARV comes in 5%–10% light. In neighborhoods like Fort Zumwalt and Francis Howell school districts where sub-$350,000 homes are still drawing multiple offers, that refinance math tends to work more often than it does in the slower-moving pockets of the City.
Reserves matter more in a BRRRR strategy than almost any other approach right now, simply because there are two financing events instead of one — the acquisition and the refinance — and each carries its own rate risk. If your appraisal comes in soft or your refinance lender tightens underwriting between the time you buy and the time you refi, you need enough cash cushion to hold the property at the acquisition-financing rate for longer than planned. Investors who model a single rate scenario for both legs of a BRRRR deal are the ones most likely to get caught short if the market moves against them mid-project.
Wholesalers
Your cash buyer pool feels rate moves too — just indirectly. When financing gets more expensive, some cash buyers rotate capital into other asset classes entirely, transactional funding costs tick up, and assignment fees face more resistance unless the underlying spread is deep. Right now, focus on properties where the numbers pencil at current hard-money rates and DSCR exit pricing — not on deals that only work if a buyer is willing to bet on rates coming down before closing.
It also pays to know your buyer list better than usual right now. Not every cash buyer is affected equally — some are funded by private capital that isn't rate-sensitive in the same way institutional or leveraged buyers are. Segmenting your buyer list by financing source, and being upfront about acquisition cost assumptions when you pitch a contract, tends to close deals faster than a generic mass blast in a market where buyers are being more selective about what they'll take down.
Run Every St. Louis Deal Through Three Scenarios
Instead of guessing which way the Fed leans today, build your underwriting to survive all three plausible outcomes. Here's the framework we recommend to clients working City, County, St. Charles, and Jefferson County deals this fall:
| Scenario | Acquisition Financing | Exit Financing | What It Means for a St. Louis Deal |
|---|---|---|---|
|
Base Case: Today's rates hold roughly flat |
8.0%–8.5% DSCR, or 11%–13% hard money |
7.5%–8.5% DSCR, or ~6.76%–7.17% conforming |
Standard underwriting. Most City/County rehabs still pencil if acquisition price reflects current comps. |
|
Upside Case: Rates ease 50–75 bps |
7.25%–7.75% DSCR |
7.0%–7.5% DSCR or conforming |
More buyers qualify above $350K; refi headroom improves in St. Charles/Jefferson County BRRRRs. Don't overpay banking on this. |
|
Risk Case: Rates rise another 25–50 bps |
8.5%–9.25% DSCR, or 12%–14% hard money |
8.0%–9.0% DSCR or conforming |
Sub-$350K buyer pool shrinks further; carry costs on stalled City rehabs climb fast. Deals only working here are too thin. |
The rule of thumb: if a deal only clears the bar in the upside column, it's not a deal — it's a wish. Underwrite to the base case, confirm you can still survive the risk case, and treat any upside as a bonus if it shows up.
A Worked Example — North City Ranch
Illustrative only — not an actual current listing
A 3-bed, 1.5-bath ranch in North City is available at $145,000. ARV: $210,000. Repairs: $30,000.
-
Base case: $145K acquisition, 25% down, $108,750 DSCR at 8.0% ≈ $797/month P&I. Rent $1,400/month; taxes, insurance, maintenance, and vacancy reserve ≈ $500/month. Cash-on-cash lands around 3%–4% if repairs are financed, 6%–7% if paid in cash.
-
Risk case: Same deal at 8.75% DSCR pricing ≈ $852/month P&I, cutting monthly cash flow to roughly $48 before repair debt service — cash-on-cash drops to 2%–3%, or negative depending on how repairs are financed.
Takeaway: this deal is marginal at today's rates and fails outright in the risk case. Either negotiate the acquisition down toward $130K–$135K, or walk.
Your 48-Hour Post-Fed Checklist
Whatever gets announced at 2:00 p.m. today, here's what actually matters for your St. Louis pipeline over the next two days:
Within 24 Hours (Today Through Tomorrow)
- Read the statement, not just the headline. Watch the vote count for dissents and any change in language around inflation and labor conditions.
- Check the dot plot. Individual member projections tell you more about the path through year-end than the September move itself.
- Watch the 2:30 p.m. press conference. Warsh has avoided forward guidance so far — any shift in tone is itself a signal worth noting.
- Track mortgage rate movement Wednesday through Friday using the FRED series or Mortgage News Daily's daily tracker linked above, rather than waiting for next Thursday's PMMS release.
- Re-run your active St. Louis pipeline if rates move 25+ basis points in either direction — recheck DSCR coverage on every deal under contract.
Within 48 Hours
-
Call your lenders. Ask directly whether DSCR pricing, hard-money terms, or underwriting standards are shifting in response.
-
Update your maximum acquisition price on every active offer. If rates rose, your ceiling drops — don't chase a number that no longer works.
-
Talk to your buyer pool if you're wholesaling. Re-price assignments honestly rather than hoping a buyer absorbs the difference.
-
Log the move. Keep a simple running record of rate changes and how you adjusted — it pays off the next time this happens, and it will happen again.
A Few Questions We're Hearing This Week
Should I pause offers until after today's announcement?
Generally, no. Sellers and agents don't hit pause just because the Fed is meeting, and a well-underwritten offer at today's rates doesn't become a bad offer because of what gets announced at 2:00 p.m. If your numbers work in the base case and survive the risk case, there's no financing reason to sit on the sidelines. The exception is a deal that's already razor-thin — if you're relying on rates dropping to make the math work, that's a signal to renegotiate the price, not a reason to wait for the Fed to save the spreadsheet.
How fast do local lenders usually reprice after a Fed move?
Retail mortgage rates typically move within a day or two of a clear policy signal, though as this week has shown, much of the move can happen before the meeting even occurs. DSCR and hard-money lenders serving the St. Louis investor market tend to adjust on a similar timeline, sometimes faster if their own warehouse lines reprice quickly. The practical takeaway is the same either way: get a fresh rate quote before you finalize an offer, rather than relying on a number your lender gave you last week.
Does a hike automatically mean St. Louis prices fall?
Not necessarily, and the data so far this year backs that up — inventory has climbed well into double-digit percentage growth while median prices have kept rising rather than falling. What a hike tends to do first is slow transaction volume and stretch days-on-market, particularly for properties that need work or sit above the sweet spot for first-time buyers. Price softening, when it happens, usually shows up with a lag and concentrates in the categories of inventory that were already sitting the longest.
The Bottom Line
Today’s Fed rate decision is background noise for St. Louis real estate investors—the financing reality you need to underwrite by was already set weeks ago by the bond market, and it’s tighter than most pro formas assume. Mortgage rates have climbed for eight straight weeks (30-year fixed at 6.76%–7.17% as of mid-September), DSCR pricing is running 7.125%–8.5% depending on credit and leverage, and the metro housing market is splitting cleanly between move-in-ready inventory that still moves fast and everything else that’s sitting longer. If your deal only clears the bar assuming rates drop or exit financing lands at 2023–2024 levels, it’s not a deal—it’s a bet on a rate cut that may not come. mortgagedaily+4
Ready to Buy or Sell in St. Louis? House Sold Easy Has You Covered!
Whether you're thinking about listing your home or exploring a cash offer, it's worth understanding all of your options before making a decision. The right choice depends on your timeline, your property's condition, and your goals. Contact House Sold Easy to discuss your situation and see what makes the most sense for you.Our St. Louis experts know every corner of this city and will make buying your dream home or selling your high-end property a breeze. Don’t miss out on the hottest market in the U.S.! Contact House Sold Easy today and let’s make your real estate goals happen!