St. Louis Real Estate Update: August 2026 Inventory Surge
Or call/text 636-525-1566. We answer 24/7.
Written by House Sold Easy Team
August 2026 was the month the St. Louis listing count stopped being a rumor. Homes sat longer, more sellers cut their asking prices, and buyers who were outbid in 2021 and 2022 finally had a few days to think. This update covers the metro numbers first, then breaks them down by submarket and by municipality, because a house in Ballwin and a house in Bevo Mill are not in the same market.
The submarket and municipal sections were folded in from our earlier inventory report, so this summer’s inventory story now lives on one page.
The Big Numbers: What's Happening in St. Louis Right Now
The definitive headline story for August 2026 is inventory growth. For years, the St. Louis metropolitan area suffered from a chronic shortage of available housing stock, which kept prices climbing upward regardless of rising interest rates. However, the latest metrics indicate a turning point.
Active residential listings across the Greater St. Louis metro area have climbed significantly. Depending on the specific micro-region within the St. Louis MSA, active listings have expanded by roughly 10% to 14.5% compared to the same period last year. This isn’t a minor statistical blip or a temporary weekend fluctuation; it represents the most substantial inventory expansion we’ve experienced since before the pandemic-era market frenzy upended traditional real estate cycles.
New listings are also on an upward trajectory. Regional associations report steady year-over-year increases in new residential single-family properties hitting the market, while independent aggregators like Redfin's St. Louis Housing Market Analysis show that buyers are finally seeing a broader selection of properties across both urban and suburban corridors.
More homes hitting the market fundamentally alters the psychological balance of transactions. It means buyers no longer have to panic-buy the first property that fits their basic criteria. Simultaneously, it means sellers can no longer rely on sloppy listing photos and an inflated price tag to net an easy win. Competition among sellers is back, and it is reshaping negotiation leverage across every pocket of the metro.
Median Prices Tell a Nuanced Story
When people hear the word "inventory surge," they often assume home prices are about to crash. But real estate in St. Louis rarely moves in monolithic directions. Instead of a market-wide collapse, median prices are telling a nuanced, split-personality story depending on how you slice the data: list prices versus sold prices, and city versus county.
Metro-Wide List vs. Sold Divergence
- Metro-Wide Median List Price: Hovering around $290,000, down roughly 3.3% from a year earlier. This represents the first meaningful list price moderation we’ve tracked in the St. Louis MSA in several years. Sellers are adjusting their expectations out of the gate.
- Metro-Wide Median Sold Price: Sitting between $310,000 and $350,000 depending on the exact MLS boundaries, showing a resilient year-over-year appreciation of roughly 4.5% to 5.1%. Why are sold prices still climbing while list prices soften? Because the homes that successfully close are heavily concentrated in turnkey, well-maintained condition, and they continue to command competitive offers.
The City vs. County Divide
Zooming into individual geographies reveals even sharper contrasts:
- City of St. Louis: Median sold prices sit around $261,000 to $265,000, reflecting a much softer, highly neighborhood-dependent appreciation rate. While historic neighborhoods like Tower Grove and the Central West End see steady action, other pockets within city limits move at a much more deliberate pace.
- St. Louis County: Median sold prices have pushed past $325,000, continuing a stronger upward trajectory supported by suburban demand in areas like Kirkwood, Webster Groves, and Chesterfield.
This divergence means pricing strategy is everything. Sellers who price their homes realistically based on recent comparable sales are receiving strong, clean offers. Those who test the upper limits of fantasy pricing are watching their homes languish.
Visualizing the Market: St. Louis Inventory & Price Trends (2026)
To better visualize how the St. Louis market has transitioned into this mid-2026 normalization phase, review the structural breakdown below. This visual layout outlines the core metrics shaping current transactions across the metro.
Median Sold Price $310K - $350K Steady 4-5% appreciation Days on Market (DOM) 44 Days Double the speed of 2021-2022
Days on Market: The Patience Factor
One of the most telling psychological metrics of a shifting housing market is how long properties take to sell. If you tried to buy or sell a home in St. Louis during the white-hot markets of 2021 and 2022, you remember properties going under contract in under two weeks, often accompanied by waived inspections and cash-over-appraisal guarantees.
Those days are firmly behind us. Current MLS data shows that the median days on market (DOM) across the greater metro area sits at 44 days, with specific city properties averaging around 47 days. Compared to the 11-to-17-day averages of recent peak years, homes are taking more than twice as long to clear.
What does this mean depending on your side of the transaction?
- For Sellers: You must prepare for a measured marketing cycle. Do not panic if your home doesn’t generate a bidding war during its first open house. Setting proper expectations with your listing agent regarding staging, professional photography, and realistic pricing prevents the dreaded "stale listing" syndrome.
- For Buyers: You finally have breathing room. You can actually schedule a second showing, bring in a qualified home inspector without feeling rushed, and negotiate repairs or closing cost credits without fearing that another buyer is hovering over your shoulder with an all-cash, no-contingency offer.
Months of Supply: Moving Toward Balance
In real estate economics, "months of supply" measures how long current inventory would last if no new homes were added to the market, calculated based on the existing pace of closed sales. A balanced, healthy real estate market typically maintains 5 to 6 months of supply, an equilibrium where neither buyers nor sellers hold absolute dictatorial control.
For several years, St. Louis operated at an exhausting 1.5 to 2 months of supply. As of August 2026, inventory levels have improved to roughly 2.4 to 3.5 months of supply across the metro area.
While this still technically favors sellers under textbook definitions, it represents a definitive march toward market balance. This shift gives buyers significantly more leverage, particularly in higher price tiers (such as homes priced above $400,000) where inventory growth has outpaced lower-tier starter homes. According to long-term forecasts from analysts like Norada Real Estate Investments' St. Louis Market Outlook, this gradual stabilization is expected to define regional housing patterns well into 2027.
Price Reductions: A Sign of Seller Reality
Another key indicator of shifting market dynamics is the frequency of price adjustments. Across mid-August 2026 tracking data, nearly 17.9% of active St. Louis listings have carried at least one price reduction since hitting the market, up roughly 1.1 percentage points compared to the same period last year.
This statistic serves as a vital signal for home sellers. The current market actively punishes overpricing. When a seller lists a property too high based on emotional attachment or outdated comparable sales from 2024, the property sits. Once it sits for three or four weeks, buyers assume something is wrong with it, forcing the seller into a reactive price cut.
Conversely, for active buyers, price-reduced properties represent prime hunting grounds. A home that has undergone a thoughtful price reduction often signals a motivated seller, someone who may be relocating for work, managing an estate, or simply eager to close. These sellers are far more likely to negotiate on repair concessions, home warranties, or closing cost assistance.
Neighborhood Spotlight: Where the Action Is
Real estate is hyper-local. National headlines rarely tell the full story of what is happening on a specific St. Louis street. Here is a breakdown of how different submarkets are performing in August 2026:
| Submarket Corridor | Typical Price Tier | Inventory Trend | Buyer Competition Level |
|---|---|---|---|
| **Central County:**Kirkwood, Webster Groves, Clayton | $350,000, $550,000+ | Stable / Tight | Moderate to High for fully updated properties |
| North County:Florissant, Hazelwood, Ferguson | $180,000, $260,000 | Gradually Increasing | Active first-time buyer and starter home demand |
| **South County:**Oakville, Mehlville, Affton | $280,000, $380,000 | Steady | Balanced; heavily favors prepared buyers with strong financing |
| **City Core:**Tower Grove, Central West End, Soulard | $250,000, $400,000 | Mixed | Highly neighborhood-specific; historic architectural appeal drives demand |
| **St. Charles County:**St. Charles, O'Fallon, Wentzville | $320,000, $450,000 | New Construction Surge | Moderate; buyers enjoy wider builder incentives and choices |
For institutional insights into broader regional commercial and residential spillover trends affecting these submarkets, regional overviews such as CBRE's St. Louis Real Estate Outlook highlight how suburban job corridors continue to influence residential demand.
Alternative Financing & Creative Solutions in Today's Market
Even with inventory ticking upward, affordability remains a central concern for many local buyers navigating mortgage rates sitting consistently in the mid-6% range. Traditional bank financing isn't the only path to homeownership in St. Louis, and savvy buyers and sellers are increasingly exploring alternative transaction structures.
At House Sold Easy, we frequently work with buyers and sellers who benefit from creative financing solutions.
- For Sellers: If you own your property free and clear (or hold substantial equity) acting as the bank allows you to secure a steady monthly cash flow with interest rates often higher than traditional bank savings yields, all while deferring capital gains taxes through installment sales.
- For Buyers: Self-employed professionals, entrepreneurs, or buyers temporarily recovering from credit blemishes who cannot immediately secure conventional institutional mortgages can negotiate direct terms with a motivated seller, allowing them to lock in a home today and refinance down the road when rates or personal financials shift.
Creative structuring takes administrative care and clear legal documentation, but in a normalized market like August 2026, flexibility wins deals that would otherwise fall apart over rigid bank underwriting guidelines.
3. Hyper-Local Analysis: St. Louis Submarkets & Neighborhoods
Because metropolitan averages combine diverse communities, analyzing submarkets individually is essential for making informed real estate decisions.
St. Louis County Core: Clayton, Ladue, Kirkwood & Webster Groves
The central and inner-ring suburbs of St. Louis County remain the most resilient sector of the market. High educational ratings, walkable commercial districts, and established architectural character sustain steady buyer demand.
- Kirkwood and Webster Groves: Move-in-ready historic two-story homes and renovated craftsman bungalows listed between $400,000 and $700,000 regularly go under contract in under 14 days. However, properties with functional obsolescence, awkward floor plans, or unaddressed foundation concerns are sitting for 30 to 45 days until sellers make $15,000 to $30,000 price corrections.
- Clayton and Ladue: Luxury single-family inventory above $1,000,000 moves steadily for turnkey new construction and modernized estates. Older mid-century stock requires aggressive cosmetic discounting before luxury buyers commit capital.
Inner-Ring Value Corridors: Affton, Maplewood & Overland
For first-time homebuyers and value-oriented move-up buyers, mid-county and south-county border suburbs are serving as primary target zones.
- Affton and Maplewood: Homes priced between $220,000 and $320,000 offer strong affordability relative to central corridor pricing. In these neighborhoods, buyers are securing contracts without excessive escalation clauses, frequently negotiating minor repair allowances or home warranty coverage during inspection periods.
- Overland and St. Ann: These northwest county communities feature substantial inventory of brick ranches and starter homes below $200,000. Properties here show higher sensitivity to interest rate fluctuations, with days on market averaging 28 to 35 days.
North County: Florissant & Hazelwood
North St. Louis County offers some of the highest cash-flow potential and lowest acquisition costs in the metro area. In Florissant, active inventory has grown by over 18% year-over-year. Buyers have substantial negotiating leverage, with sellers frequently agreeing to pay 2% to 3% in buyer closing cost credits or funding temporary 2-1 mortgage rate buydowns.
St. Louis City: Historic Neighborhoods vs. Downtown Lofts
According to recent urban transaction tracking, the City of St. Louis maintains a median closed sale price between $259,000 and $265,000. However, neighborhood divergence within the city limits is pronounced:
- Tower Grove South, Shaw, and Soulard: Brick historic homes, updated duplexes, and multi-family fourplexes continue to see consistent demand driven by walkability, park access, and vibrant independent commercial districts. Fully renovated properties command $350,000 to $500,000+.
- Central West End (CWE): High institutional employment from the Washington University Medical Campus and Barnes-Jewish Hospital maintains a solid floor for luxury single-family homes and historic condos.
- Downtown St. Louis (63101 / 63103): The residential loft market continues to face longer absorption periods. Redfin Downtown St. Louis market metrics show median days on market exceeding 90 to 110 days for high-rise condos, providing buyers with significant room to negotiate deep discounts on purchase price and HOA concessions.
St. Charles County: O'Fallon, St. Peters & Wentzville
West of the Missouri River, St. Charles County remains a high-volume suburban market characterized by newer subdivisions, master-planned developments, and modern public infrastructure.
- August 2026 MARIS/InfoSparks tracking shows St. Charles County holding 2.02 months of inventory, slightly tighter than St. Louis County’s 2.14 months.
- In Wentzville and O'Fallon, national and regional homebuilders are competing directly with resale listings by offering mortgage rate buydown incentives (often buying 30-year rates down into the high 5% range for the initial years of the loan). Resale sellers in these areas must ensure their homes are staged and updated to compete effectively against builder concessions.
8. Navigating St. Louis Real Estate by Municipal Jurisdiction
Operating effectively in the St. Louis real estate ecosystem requires understanding the regulatory and tax framework governing different local jurisdictions:
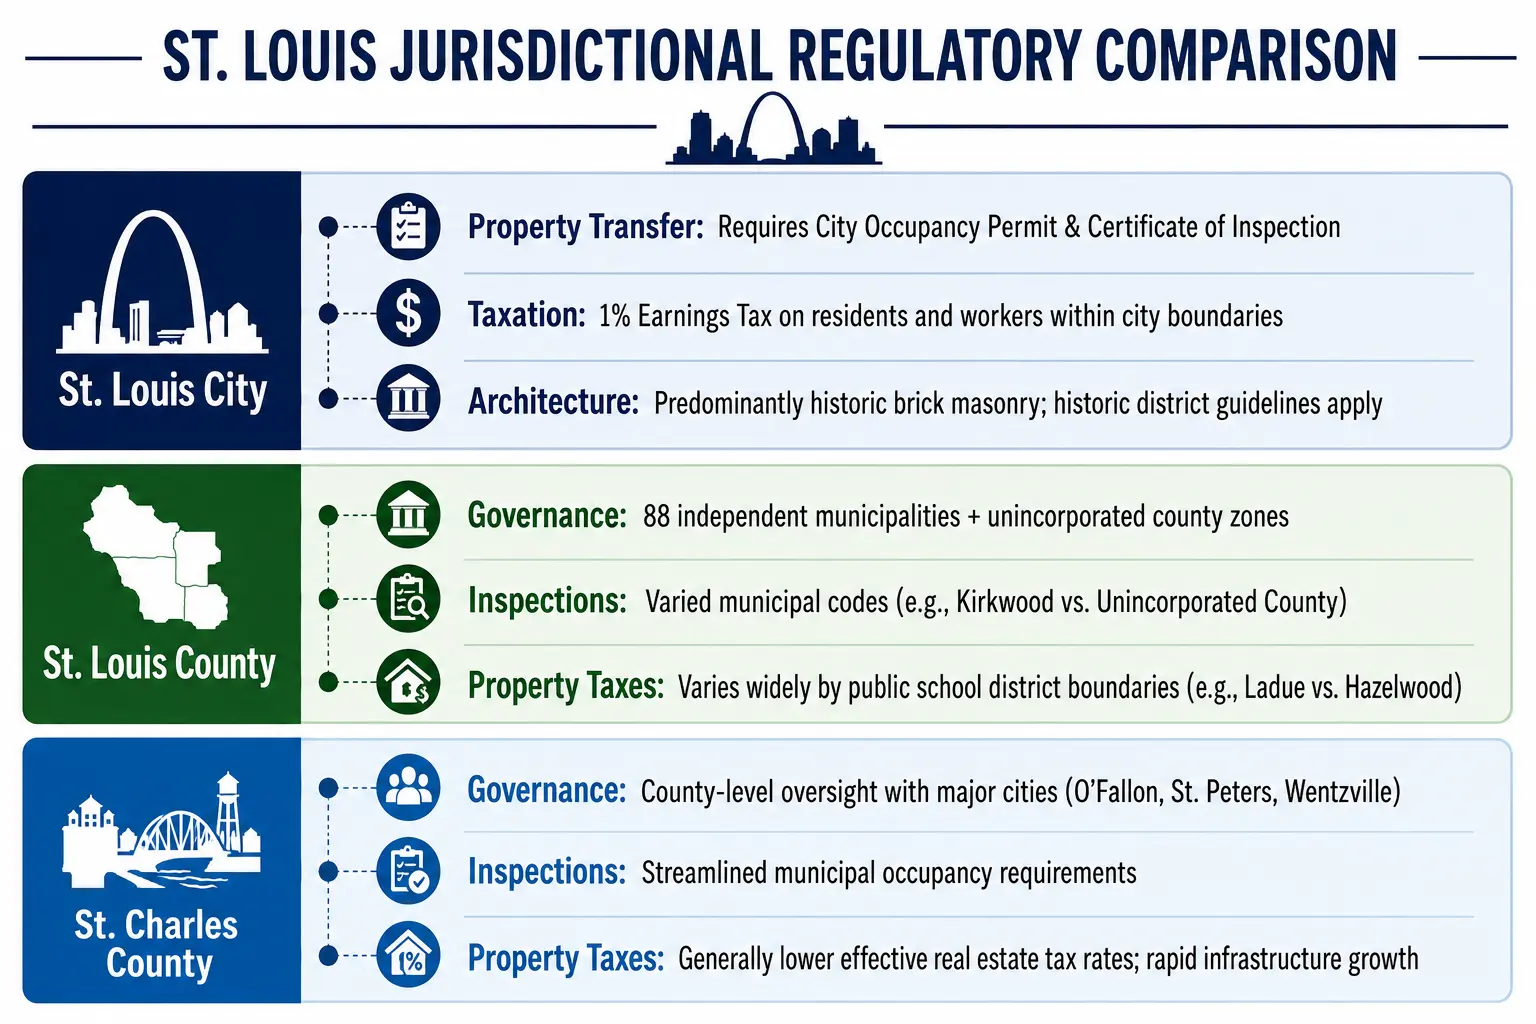
Understanding these distinctions ensures that buyers accurately calculate their all-in monthly payment, sellers avoid closing delays caused by municipal compliance re-inspections, and investors budget correctly for long-term operational costs.
What This Means for You: Actionable Strategies
Knowing the data is only half the battle; knowing how to act on it is what secures a successful transaction.
If You're a St. Louis Buyer
- Take Your Time, But Be Prepared: With inventory up 10%+, you don't need to rush into a bad purchase. Get fully pre-approved so that when you do find the right house, you can move decisively.
- Target Price-Reduced Homes: Look for properties that have been on the market for 30 to 45 days. These sellers are often motivated and ready to negotiate terms that favor you.
- Inspect Thoroughly: Use your newfound market leverage to conduct comprehensive home inspections and request necessary repairs or credits without fear of losing the house to a competing cash buyer.
If You're a St. Louis Seller
- Price Right from Day One: Overpricing in an expanding inventory market is a fatal error. Price your home based on actual closed comps from the last 60 days, not peak-market wishes.
- Invest in Curb Appeal and Staging: Because buyers have choices, homes that show poorly or feel dated will sit. Clean, modern, move-in-ready properties still command top dollar.
- Expect a 44-Day Runway: Understand that the days of the 48-hour cash sale are largely gone outside of hyper-competitive micro-pockets. Build a patient, steady marketing timeline with your agent.
If You're a St. Louis Investor
- Analyze City vs. County Yields: Slower appreciation rates in certain city neighborhoods can offer attractive entry caps for long-term rental holds, while suburban county corridors provide stable appreciation but higher initial acquisition costs.
- Watch Commercial and Logistics Corridors: As commercial developments and industrial logistics sectors expand across the metro, residential pockets adjacent to these employment hubs continue to experience resilient tenant demand.
 Make Us a Preferred Source on Google
Common Questions
Does the August 2026 inventory jump mean prices are crashing?
More listings and more price cuts point to a slower market. A crash would show up as falling closed prices across the metro, and the August data above does not show that.
Which St. Louis homes feel the inventory surge most?
Dated homes and homes priced off last spring sit longest. The submarket section above walks through the County, City, and St. Charles County differences.
Can I skip showings if my house is sitting?
Yes. Send us the address or call 636-525-1566. We buy as-is, and with clear title a close usually takes about two weeks.